Fargo-Moorhead Commercial Real Estate 2026: Andy Westby · Fargo INC!
Businesses
Examining The Market With Andy Westby
Goldmark Commercial Real Estate’s Andy Westby breaks down the numbers behind Fargo-Moorhead’s industrial boom, the office squeeze and what owners should weigh before they lease, buy or build.
In shortGoldmark Commercial's Andy Westby details Fargo-Moorhead's commercial real estate conditions, highlighting a 2.09% industrial vacancy rate, struggling traditional office space, and a widening gap between construction costs and achievable rents.
3 things to know
1Industrial space is the tightest sector at 2.09% vacancy, with leasing activity up roughly 412% in the first 8+ months of 2026 versus the same period in 2025.
2Office vacancy sits around 10.1%, with the median office listing on the market for approximately 440 days; larger, older, and inflexible suites face the greatest challenges.
3Current metro-wide average asking rents of ~$10.50 PSF industrial, ~$20.25 PSF retail, and ~$19 PSF office often do not support speculative new construction given rising costs.
Generated by Claude · grounded in this articleNever used on sponsored content
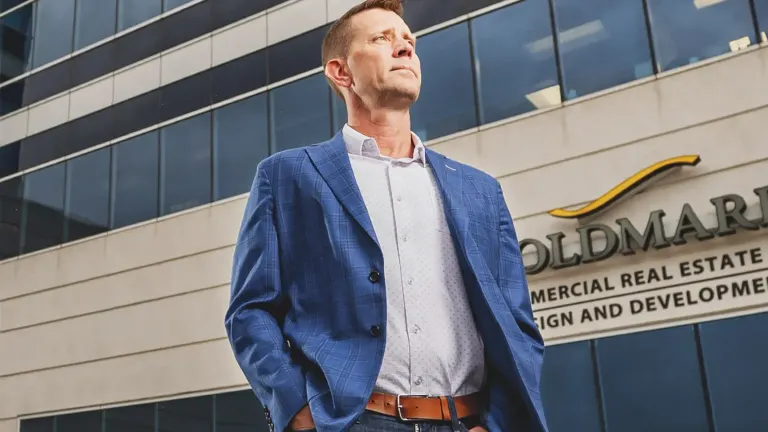
Andy Westby has spent his career working with businesses, first in technology and, since 2015, in commercial real estate. As president and managing broker of Goldmark Commercial Real Estate, he brings experience in office and industrial sales and leasing, along with commercial and agricultural land transactions. A North Dakota State University graduate who grew up around his family’s farming, real estate, and auctioneering businesses, Westby joined Goldmark after 15 years in the technology industry and assumed his current leadership role in 2019.
For this issue, Westby provided a detailed look at the numbers shaping commercial real estate across Fargo, West Fargo and Moorhead. In the following interview, he explains the differences behind those numbers, from tightening industrial availability to the challenges facing traditional office space. He also explores the gap between construction costs and achievable rents, commonly overlooked occupancy expenses, and why a business owner’s decision to lease, buy or build should begin with the business plan, not the building.
Which number best describes the current state of the Fargo-Moorhead commercial real estate market?
If I had to choose one number, it would be the 2.09% industrial vacancy rate. That illustrates just how tight the industrial market has gotten, particularly after what was a rough 2025 for industrial leasing activity. During the past 9 months, industrial leasing activity has boomed, and is up approximately 128% YOY, with nearly 1 million square feet leased through the MLS in the past year.
That number doesn’t describe every property type, however. Office vacancy has struggled some, hovering in the low double digits for some time now, while retail vacancy is relatively healthy at around 5.0%, so each asset class is in a different position at this point in time.
What has changed most significantly since 2019?
The most significant change has been the growing disconnect between the cost of developing new commercial property and the rents many tenants are accustomed to paying. Construction costs, land prices, interest rates, insurance, and other operating expenses have all increased substantially since 2019. Lease rates have increased too, but often not enough to make speculative construction economically feasible.
We have also seen industrial demand become a much larger driver of the market, while office users have become more selective about how much space they need and what type of environment will bring employees back to the workplace.
Retail has held its own and rebounded quite well for the most part after taking a big hit at the onset of COVID in early 2020.
Which property type currently has the strongest fundamentals?
Industrial clearly has the strongest fundamentals. The current MLS vacancy rate is approximately 2.09%, compared with 4.96% for retail and 10.11% for office. Industrial leasing activity over the first 8+ months of 2026 is approximately 861k square feet, an increase of roughly 412% from the first 8+ months of 2025.
Demand is especially strong for buildings that provide a practical combination of warehouse space, satisfactory office finish, good loading, adequate clear height, outdoor storage, and convenient access. Those requirements can be difficult to satisfy simultaneously, which makes quality industrial properties particularly valuable.
Which part of the market faces the greatest challenges?
Traditional office space faces the greatest challenges. That does not mean there is no office demand, but tenants are generally more deliberate about the amount and quality of space they occupy, with many tenants reducing their footprints or waiting longer before making decisions.
The current office vacancy rate is approximately 10.1%, and the median office listing has been on the market for about 440 days. Class A office space is experiencing an even longer reported median marketing period and has seen a huge slowdown in lease activity over the past few quarters. Buildings with large floorplates that don’t subdivide well (10k+ SF) are also very hard to lease right now, as large users do not seem to be in the market at this time.
Where is the market currently undersupplied or oversupplied?
The industrial market quickly went into an undersupplied status given the rush of leasing activity we have seen in 2026. That is particularly true for mid-to-larger-sized spaces with dock access and outdoor storage. Larger industrial users will have difficulty right now finding spaces that meet their requirements.
The market is comparatively oversupplied in certain categories of traditional office space, especially older or larger office suites that have not been updated. I would not describe all office space as oversupplied, however. There can still be limited availability for smaller, move-in-ready offices in desirable locations. The oversupply is concentrated in particular building types, sizes, and conditions rather than distributed evenly across the entire office market.
What sizes and types of spaces are tenants seeking most often?
Demand is generally strongest for spaces that allow a business to avoid taking on substantially more square footage than it needs.
In industrial, we frequently see demand for approximately 2,500 to 10,000 square feet, often with one or more overhead doors, limited office finish, and some ability to store materials or equipment outside. There is also continued demand from larger industrial users, but those searches tend to be more specialized and can take longer because of requirements related to dock access, clear heights, power, yard space, and more.
Office users commonly seek smaller, efficient suites often in the 1,500 to 5,000-square-foot range. Most focus on suites that are already finished or require minimal renovation. Retail demand is often concentrated in roughly 1,200 to 4,000 square feet blocks, with high visibility, good signage, ample parking, and strong access often more important than just achieving a fair rent.
Which parts of the metro are seeing the strongest demand?
Demand continues to follow population growth, transportation access, and strong traffic patterns. South/southwest Fargo and West Fargo remain attractive for retail, service businesses, and medical users because of residential growth and strong traffic patterns. The I-94 and I-29 corridors continue to be important for businesses that need regional access as well.
North Fargo, western West Fargo, and eastern Moorhead are all receiving attention for industrial development because of their strong interstate access and availability of larger sites. West Fargo has absorbed much of its commercial land, with the remaining pockets seeing strong demand, while Moorhead continues to see resurgence and investment in their Downtown corridor.
Ultimately, demand is becoming increasingly property-specific. Access, visibility, parking, area amenities, and building functionality can matter more than the city name on the address in many cases.
Is there enough industrial, warehouse and flex space to meet current demand?
Not in most categories. The overall industrial vacancy rate is only about 2.09%, so tenants with flexibility may find options, but businesses with specific requirements often have very few legitimate choices.
The shortage is most noticeable in functional mid-sized or larger industrial spaces, but even small-bay industrial demand can be limited depending on the specific area of the metro you are looking for. A tenant may see several properties advertised, but after eliminating spaces that are too large, too small, poorly configured or missing an essential feature, the actual list of viable alternatives can become very short.
Are current lease rates high enough to justify new construction?
In many cases, no…at least not for purely speculative construction. Current ALL-IN average asking rents metro-wide are approximately $10.50 PSF for industrial, $20.25 PSF for retail, and $19 PSF for office. Those average rates rarely support new development in certain locations or for certain building types, as construction costs, financing costs, and required investment returns have increased considerably.
New construction is most feasible when a developer has a committed tenant, a longer lease term, appropriate annual rent increases and limited tenant-specific improvements, or when the owner-user values ownership beyond the property’s immediate investment return. Speculative projects must be carefully sized and positioned because the rent required to justify construction may be noticeably higher than the rent on older competing properties.
What are the biggest misconceptions about the local commercial real estate market?
One misconception is that a single vacancy rate tells the whole story. Commercial real estate is not one market. Office, retail, and industrial behave differently, and even within those categories, results vary substantially by location, size, condition, and functionality. You really must analyze a property and the market by multiple factors to determine if the deal you are getting into is a good or bad one.
People also frequently underestimate the total cost and time involved in occupying a commercial property. Base rent is only one component. Costs such as CAM (which usually includes taxes, insurance, etc.), utilities, tenant improvements, furniture, equipment, and even parking costs can materially change the economics. A space that appears inexpensive may be the more costly option once all expenses are considered.
Finally, some assume that commercial property values should move in the same direction (i.e. UP!) every year. Commercial property is valued on income, lease quality, occupancy, operating expenses, and investment returns. If a property’s income hasn’t changed in years but the expenses have gone higher, along with cap rates increasing because of rising interest rates, buildings can easily be worth less today than they were just a few short years ago. Many owners find that a bitter pill to swallow.
What should local business owners understand before deciding whether to lease, buy, build or sell?
The decision should begin with the business plan, not the building. Owners should consider how much space they actually need, how quickly they may grow, how specialized the property must be, how much capital they can commit, and how long they expect to remain in the location.
Leasing generally provides more flexibility and requires less capital upfront. Buying can build equity and provide greater control, but it also ties up cash and makes the business responsible for maintenance and capital improvements. Building offers the best opportunity to create exactly what the business needs, but it typically requires the most time and capital.
Owners should also compare the complete economics rather than simply comparing monthly rent to a mortgage payment. That analysis should include tenant improvements, CAM, taxes, insurance, maintenance, financing costs, down payment, opportunity cost, and the potential long-term value of the property.
Additionally, businesses should begin the process earlier than they think necessary. Lease negotiations, purchase due diligence, financing, design, permitting, and construction can take months, or even years. Starting early gives the business more options and far more negotiating leverage. A commercial real estate decision can affect a company’s cash flow, operations and ability to grow for many years, so it deserves the same level of planning as any other major business investment.
Most importantly, businesses should also surround themselves with experienced professionals who understand the local market and have access to objective, reliable data. Asking rents and sale prices only tell part of the story. A knowledgeable commercial real estate advisor can help a business understand actual market conditions, identify opportunities that may not be publicly advertised, evaluate competing options, negotiate appropriate terms, and anticipate issues that could otherwise become costly. For a new development, that team may also need to include experienced professionals in design, construction, financing, land use, and legal matters.
Key takeaways
Industrial is the metro’s strongest and tightest property sector. With industrial vacancy at just 2.09%, the Fargo-Moorhead market has very limited available warehouse, flex, and manufacturing space, especially mid-sized and larger buildings with loading docks, sufficient clear height, outdoor storage, and strong interstate access. Industrial leasing has surged in 2026, making functional space increasingly difficult for tenants to secure.
The market is highly segmented, with office facing the most pressure. Commercial real estate cannot be defined by one vacancy figure. Retail remains relatively healthy at about 5.0% vacancy, while office vacancy is roughly 10.1% and traditional office listings are taking much longer to lease. Demand is strongest for smaller, move-in-ready office suites, while older, larger, and less-flexible office spaces face the greatest oversupply and leasing challenges.
Higher development costs are reshaping business decisions and limiting new supply. Since 2019, rising construction costs, land prices, interest rates, insurance, and operating expenses have outpaced rent growth in many cases. As a result, speculative development is often difficult to justify unless a project has a committed tenant or specialized ownership strategy. Business owners considering leasing, buying, building, or selling should evaluate total occupancy costs, not just rent or mortgage payments, and begin planning early to preserve options and negotiating leverage.
Editor of Fargo INC! — covering the founders, companies, and ideas shaping business in Fargo-Moorhead. Eleven years in, still no opinions, no politics, all business.