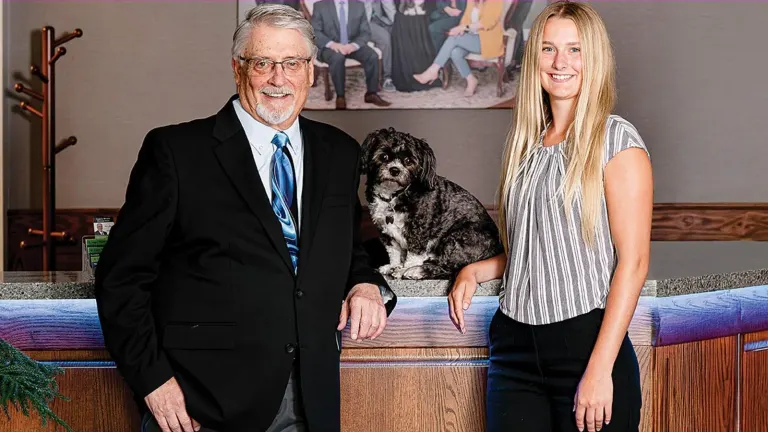
(left to right) President & LPL Financial Advisor Paul Meyers & Non-Registered Financial Assistant Amanda Waletski
After years of regular paychecks and retirement contributions, the transition into retirement brings a different set of questions. How much can you spend each month? What happens to an old employer’s retirement plan? And how do you know whether the money you’ve saved can support the life you want?
At Legacy Wealth Management, those conversations begin with a person’s circumstances and goals. Paul Meyers, the firm’s president and an LPL Financial Advisor, founded the company in 2010 and brings more than 30 years of financial services experience. Here, the Legacy Wealth team addresses four questions about preparing for retirement and organizing the assets accumulated along the way.
How do I know if I have enough money to retire?
Start by looking at your resources alongside your expected expenses. Legacy Wealth’s team reviews retirement plans, savings, IRAs, and other assets, then discusses what retirement would look like for you.
That conversation matters because the amount someone needs depends on the life those savings will support. Travel, hobbies, and time with family may shape your plans, while health care and other ongoing expenses also need attention.
The amount someone needs depends on the life those savings will support.
From there, the team compares potential retirement income with anticipated spending and develops a strategy around the findings. The review helps identify where you stand and whether there are shortfalls to address before leaving work.
There is no cost for an initial meeting, giving people an opportunity to ask questions and better understand their situation before making a retirement decision.
I’m preparing to retire. What happens to my 401(k), and can I receive money each month?
Legacy helps clients understand their retirement plan choices and how those choices fit into an income strategy. One option the team discusses is rolling eligible retirement assets into an individual retirement account, or IRA.
The details matter. A properly completed rollover of eligible pretax retirement funds into a traditional IRA generally preserves their tax-deferred status. Moving pretax money into a Roth IRA generally creates taxable income. Fees and account features should also be considered before making a move.
Legacy also helps clients evaluate when to begin Social Security and can arrange monthly distributions from investment accounts. The broader planning question is how those withdrawals and other income sources will work together to support retirement expenses.